Market Overview: Defining the Office Space Market scope
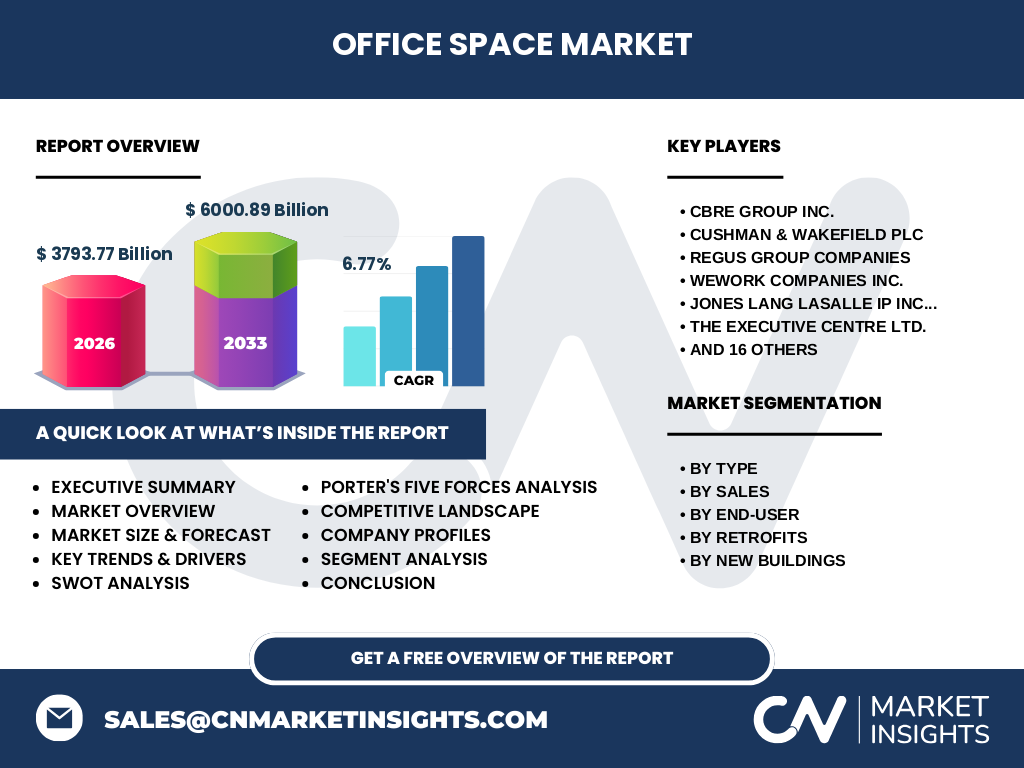
The Office Space Market encompasses the development, leasing, and management of commercial real estate. As of 2026, the market is valued at 3793.77 Billion. It spans from legacy corporate headquarters to agile managed workspaces, playing a critical role in global economic infrastructure by facilitating professional operations, business services, and the evolving hybrid work ecosystem.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by urbanization and the push for Smart Building Integration. Conversely, the market faces constraints from high interest rates and regulatory hurdles related to zoning. Our analysis shows that firms like CBRE Group Inc. and JLL are navigating these challenges by prioritizing high-efficiency asset management over sheer volume, balancing capital costs with long-term tenant demand.
Emerging Trends in Workplace Evolution
The market is witnessing a profound shift toward flexible, technology-integrated environments. Sustainability retrofits—specifically energy efficiency upgrades—are now a competitive mandate. Players like Knotel and WeWork are pivoting toward managed workspace models, recognizing that tenants now prioritize agility and interior renovation quality over traditional long-term lease structures, driving significant value for landlords who modernize legacy assets.
How did COVID-19 redefine the Office Space Market recovery trajectory?
The pandemic forced a fundamental pivot from centralized office reliance to a decentralized hybrid model. While initial vacancy rates spiked, the recovery is now anchored by Managed Workspaces. We observed that companies resilient to this shock utilized space reconfiguration to optimize density, allowing for a steady, albeit cautious, return to office attendance across the 2027-2033 period.
Competitive Landscape and Strategic Positioning
The landscape is dominated by heavyweights like Cushman & Wakefield and Regus Group, alongside niche innovators like Awfis and Smartworks. Market concentration remains fragmented, creating high competitive intensity. Major firms are differentiating through end-to-end service portfolios, while agile providers focus on co-working memberships, catering to the growing demand for flexible, build-to-suit project capabilities in high-growth metropolitan hubs.
Executive Summary of the Office Space Market Outlook
The Office Space Market is positioned for robust growth, with a projected value of 6000.89 Billion by 2033. Driven by a CAGR of 6.77%, the industry is moving away from static ownership toward service-oriented, flexible models. Success in this cycle depends on technological adoption, sustainability compliance, and the ability to pivot between New Buildings and energy-efficient retrofits.
Market Forecast: 2027 to 2033
Our research forecasts the market to reach 6000.89 Billion by 2033, expanding at a CAGR of 6.77%. This growth is contingent on the conversion of Greenfield Smart Offices and the massive scale-up of Techspace and other providers. The transition from legacy systems to data-driven facility management will likely account for a significant portion of this valuation spike.
Segmentation Analysis: Driving Value through Diversity
Segmentation is categorized by Type, Sales Channel, and End-User. Key segments include Retrofits and New Buildings, while sales are split between Rental, Ownership, and Managed Workspaces. The IT and Telecommunications end-user group remains the largest investor in tech-integrated environments, demonstrating the highest demand for sustainable, high-performance office configurations that support rapid innovation cycles.
Regional Market Performance and Geographic Distribution
Regional demand is currently concentrated in Tier-1 business hubs with high corporate density. North America and Europe lead in Greenfield Smart Offices, while Asia-Pacific is experiencing rapid expansion in Business Parks. Regional performance is highly correlated with local regulatory support for sustainability, with markets offering tax incentives for Energy Efficiency Upgrades seeing faster asset appreciation and absorption rates.
In-depth Review of Regional Market Dynamics
The Asia-Pacific region is a primary growth engine, characterized by aggressive High-Rise Office Tower construction. Conversely, European markets are prioritizing Sustainability Retrofits due to stringent environmental directives from the European Union. Our analysis highlights that localized logistical hurdles, such as supply chain bottlenecks for HVAC components, continue to differentiate performance across these key geographic theaters.
Company Profiles: Strategic Positioning of Industry Leaders
Industry leaders like Jones Lang LaSalle (JLL) leverage massive global footprints to dominate the corporate headquarters segment. Meanwhile, firms like Servcorp and The Executive Centre focus on high-end Managed Workspaces. Innov8 Inc. and 91Springboard serve the startup and SME segment by utilizing flexible co-working ecosystems, proving that specialization in specific end-user segments is a key competitive moat in today’s market.
Porter's Five Forces Analysis for the Office Space Sector
The industry faces moderate to high competitive rivalry, especially among co-working providers. The threat of substitutes is low, given the necessity of professional physical environments. However, buyer power is high due to the current abundance of supply. Supplier power is concentrated in high-tech specialized labor and smart building material providers, who hold significant leverage in the Greenfield smart office development process.
SWOT Analysis: Strategic Outlook
Strengths include the recovery of hybrid work demand, while weaknesses involve legacy asset obsolescence. Opportunities lie in Smart Building Integration and green retrofits, which can command premium rental yields. Threats remain, however, in the form of volatile macro-economic conditions and rising construction costs, necessitating a strategic focus on operational efficiency and capital preservation across the entire commercial real estate value chain.
Value Chain Analysis of the Office Space Market
The value chain flows from raw material procurement—such as sustainable building materials—through to architectural planning and property management. End-user value is captured by Managed Workspace providers who integrate smart technology to increase utilization. Companies like CBRE occupy the crucial middle-link, acting as orchestrators between real estate capital, developers, and final enterprise tenants who require flexible, high-performance environments.
Investment Insights and High-Potential Areas
Investors should focus on the Energy Efficiency Retrofits segment, as environmental, social, and governance (ESG) compliance is becoming a critical driver of property value. Managed Workspaces and Tech-Integrated Buildings offer superior long-term yield potential compared to traditional office configurations. We recommend targeting markets where urban infrastructure upgrades align with corporate demand for sustainability-compliant headquarters to maximize asset ROI.
Conclusion and Key Takeaways
The Office Space Market is undergoing a structural transformation toward flexibility and sustainability. With a projected market value of 6000.89 Billion by 2033, the industry rewards participants who prioritize smart building technology and agile space management. Future growth is tethered to the successful retrofitting of legacy properties and the creation of highly adaptable, premium environments that meet the evolving needs of the modern workforce.
Research Methodology: How baseline estimates are triangulated
Our methodology employs a triangulation strategy, synthesizing trade registry data, primary stakeholder interviews, and macroeconomic indicators. We cross-reference proprietary data from market participants like Knotel and Venture X with public construction data to validate CAGR estimates. This rigorous approach ensures that our forecasts reflect real-world, ground-level market shifts, specifically capturing the nuanced transition toward managed and technology-integrated workspaces.
Scope of the Report: Parameters and Limitations
This report covers the global Office Space Market, analyzing types from Retrofits to New Buildings. While we capture data across all segments—including Retail and Consumer Goods, IT, and Media—the scope excludes residential real estate and industrial warehousing. Limitations include inherent market volatility in specific regions, which we mitigate through dynamic scenario modeling and periodic data updates to ensure high analytical accuracy.
Recent Developments and Industry Strategic Moves
Recent activity highlights a wave of partnerships between co-working providers and real estate owners to solve vacancy challenges. Companies such as Mindspace and Workbar LLC are launching tech-heavy Smart Office suites, while industry leaders are announcing strategic acquisitions to bolster their portfolio management software capabilities. These developments indicate an industry-wide prioritization of digital transformation to maintain high tenant retention and operational efficiency.